Vacation Homes: Conversations Before Paperwork
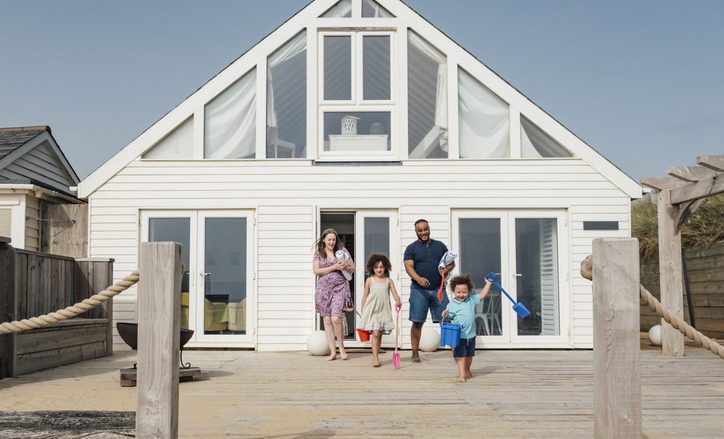
Families with the good fortune of owning a vacation home need to put extra attention into decisions about “if and how” it will be inherited by the next generation. While formal arrangements for gifting all kinds of property are an important aspect of estate planning, vacation homes deserve particular clarification, given the unique memories and emotions that tend to be wrapped up in them. Estate planning professionals encourage realistic and concrete conversation among family members in preparation for decisions about the future of a treasured vacation home.
Reality Check: Can’t The Kids Just Work It Out?
It’s wise to understand that multiple beneficiaries have the same basic options as a single beneficiary who inherits a home, with the added challenge that they must agree on how to proceed with the upkeep of the home (e.g. utilities, insurance, security, etc.) mortgage if there is one, or sale and division of proceeds. Vacation homes can be particularly challenging, especially if some beneficiaries live closer to it and use it more frequently, or have greater attachment to it.
Typically, a whole lot more than paperwork is key to avoiding heartache and conflict over the vacation home down the road. At Kiplinger Denise McClain, JD, CPA, points out that while legal documents are ultimately essential for completing estate plans, the first step is getting clear on the interests of the next generation vis a vis a vacation home:
- A family vacation home isn’t just an asset on a balance sheet. It’s where holidays happen, where grandchildren learn to fish or ski, and where family traditions and values get passed down almost as much as the property itself.
- A vacation home can carry sentimental meaning that a typical asset does not, which is exactly why it deserves a deliberate plan rather than an assumption that “the kids will work it out.”
Specifically, before making decisions about the future of a vacation home, McClain urges the current owners to have a clarifying conversation with the next generation, and keep in mind: “Sometimes the most practical plan is to sell the property and divide the proceeds, especially if heirs live far away, have different financial situations, have challenging relationships with each other or simply don’t have the same attachment to the property as the original owners.” It’s also wise to make sure that everyone involved specifically understands the costs involved in maintaining the vacation home, since failure to do so can seed conflict down the road:
Property taxes, insurance, maintenance and repairs don’t pause when the owners pass away, and often the children were not aware of how much it cost to maintain the property. Someone has to keep paying, and disagreements over who pays what — and how much — can quickly become a source of family conflict. Sharing actual numbers related to expenses is essential to helping the next generation make sound decisions.
Based on a realistic understanding of family interests and intentions, McClain suggests these practical steps related to securing the future of a vacation home:
- Put usage and expense expectations in writing. Even within a formal ownership structure, clear expectations give family members something concrete to point back to when questions arise. Some families even use an app or shared calendar to reserve times and track usage.
- Name a decision-maker or manager. Whether it is one heir, a rotating role or an outside property manager, someone should have clear authority to handle day-to-day issues.
- Revisit the plan periodically. Family circumstances change. Children marry, move or have children of their own, financial situations evolve and the property itself may become more expensive to maintain. A plan that made sense 10 years ago may not fit the family today.
Good To Know: Legal Tools
Obtaining guidance from an estate planning attorney will help you decide on the right legal structure for carrying out your intentions. There’s no one right way—and plenty of options, including these:
- A trust. Placing the property in a revocable living trust can help it pass to heirs without going through probate and allows the original owners to set clear terms for how the property should be used, maintained or eventually sold.
- An LLC or family entity. Some families place the vacation home into a limited liability company or family limited partnership, with each heir holding a membership share rather than a direct deed interest. A manager can be appointed with primary decision-making authority. This can make it easier to set rules around usage and buyouts….
- A co-ownership or usage agreement. Whether or not a trust or LLC is used, a written agreement spelling out how the home will be used and paid for is one of the most practical tools available. It can address a usage schedule, how expenses are split, what happens if someone wants out and who has final say on big decisions….
Good To Do: Carefully Designate Fiduciaries
Another key aspect of proactive estate planning is the careful designation of the fiduciaries responsible for administering the arrangements. If you write a will, you will name an executor (or personal representative in some states) to settle your estate and distribute assets. If you create a trust, you will name a trustee to manage and safeguard trust property for your beneficiaries. By selecting and preparing your fiduciaries ahead of time, you can ward off the potential for conflict and unnecessary stress down the road.
Because fiduciaries manage sensitive assets and court-monitored affairs, they may be required to secure estate bonds before commencing their duties. An estate bond is a type of fiduciary bond—a formal financial guarantee in the form of a three-party contract between the court, the fiduciary, and a surety company—that ensures the estate and its beneficiaries are protected against mismanagement, fraud, or error.
Navigating the bonding process doesn’t have to slow down estate planning and administration. Colonial Surety Company makes it easy, fast, and affordable for executors, trustees, and personal representatives to obtain estate and all types of fiduciary bonds.
Fiduciary, Executor, Personal Representative, Trustee and Estate Bonds Right Here
Estate Law Practice?
Estate planning attorneys can efficiently help all their clients secure court and fiduciary bonds with a few clicks on The Partnership Account® for Attorneys.
Just select the bond needed, send it to your client for payment, and then download, e-file or print the bond. Our fiduciary bonds include: administrator, estate, executor, guardian, personal representative, probate, surrogate, trustee, conservator and the list goes on. Court bonds include: appeal, supersedeas, injunction, replevin, receiver and more.
Sign up is free and fast, right here: The Partnership Account® for Attorneys.
In business since 1930, Colonial Surety Company is rated “A Excellent” by A.M. Best Company, U.S. Treasury listed, and licensed for business everywhere in the USA. Our customers have awarded us a 4.8 Trustpilot score.Whenever and wherever you need a bond, trust Colonial Surety Company www.colonialsurety.com